All Categories
Featured
Comprehensive Guide to 2026 Medicare Part D Enrollment

Evaluating Indexed Universal Life Benefits for Retirement
Explaining How Whole Life Insurance Protects Your Future
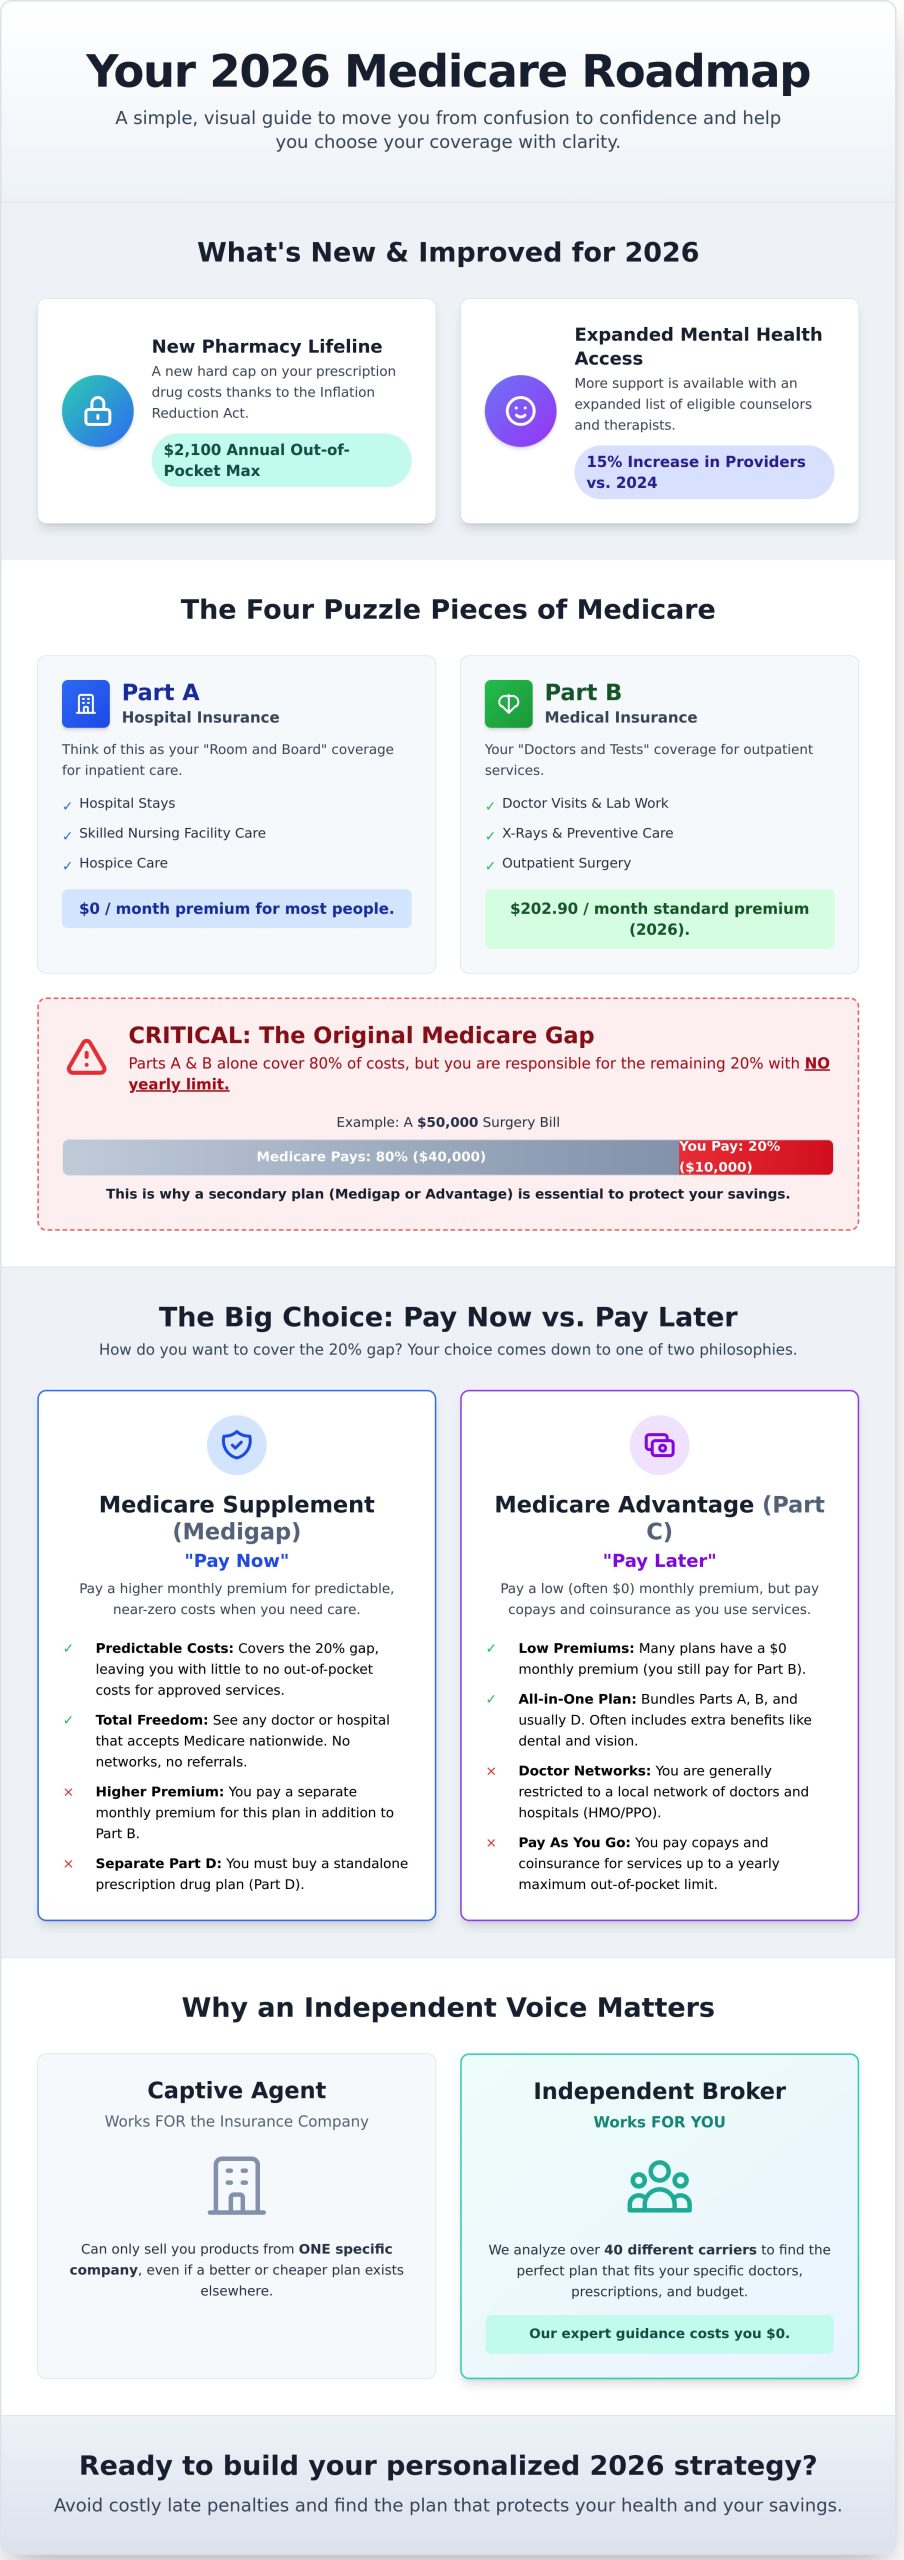
As you compare Medicare Supplement insurance coverage plans, think of how much healthcare you require, how frequently you go to the doctor and how much you can pay for to pay towards your medical bills yourself. Each Medigap plan has a different level of protection, so you need to discover one that fits your specific requirements.
Medigap plans pay for some or all of your staying expenses, depending on your strategy letter. Top plans Part A coinsurance Yes Yes Yes Part B coinsurance Yes Yes Yes Blood transfer (3 pints) Yes Yes Yes Part A hospice care Yes Yes Yes Proficient nursing center Yes Yes Yes Part A deductible Yes Yes Yes Part B deductible Yes Part B excess charges Yes Yes Yes = 100% Other strategies Part A coinsurance Yes Yes Yes Yes Yes Yes Yes Part B coinsurance Yes Yes Yes Yes 50%75% Yes Blood (3 pints) Yes Yes Yes Yes 50%75% Yes Part A hospice care Yes Yes Yes Yes 50%75% Yes Skilled nursing center Yes Yes 50%75% Yes Part A deductible Yes Yes Yes 50%75%50%Part B deductible Yes Part B excess chargesForeign travel emergency80%80%80% Yes = 100% This can give you peace of mind because you will not be shocked by high medical costs.
Plans F and C have better protection than Plan G, but you can't get them if you're a new enrollee. Plus, these plans might not save you cash because of their high monthly rates. Insurance coverage business can utilize your health history if you get a strategy outside the 6 months around your 65th birthday, called the "initial registration period." If you purchase a plan with low protection when you're 65 and later choose to update to something much better, such as Strategy G, business may quote you a high rate or deny you coverage entirely.

Strategy G has the very best coverage for the majority of elders and others on Medicare. After you pay this, Strategy G will spend for healthcare such as doctor gos to, blood tests or outpatient medical treatment. Benefits and drawbacks of Plan G Popular strategy that covers almost all of your health costs Typically a better worth than Plan F Rates can be pricey, at $180 monthly, usually Cheaper plans may be a much better offer if you rarely visit the doctor Plan F has the best coverage of any Medigap strategy overall.
Senior Hearing Aid CoverageBenefits and drawbacks of Strategy F Spends for nearly all medical expenses High monthly rates Not readily available to brand-new Medicare enrollees Plan N has similar coverage to Plan G but costs less. With Plan N, you have to pay $20 for physician visits and $50 for journeys to the emergency clinic.
Protecting Your Legacy With Burial Insurance
Pros and cons of Strategy N Yes Covers almost all of the costs you are accountable for with Medicare Yes Strategy N costs about $137 per month, which is $43 each month less than Plan G Bonus costs you're accountable for paying when you visit the medical professional could cancel out cost savings You may have extra fees if your doctor does not accept the rates set by Medicare High-deductible Plan G has the least expensive monthly rate of any Medigap policy.
Keep in mind, business can charge greater rates or reject coverage since of your health history if you alter Medicare Supplement prepares outside the six months around your 65th birthday. That indicates you may be stuck to a high-deductible Plan G when you're older and in even worse health, costing you more in the long run.
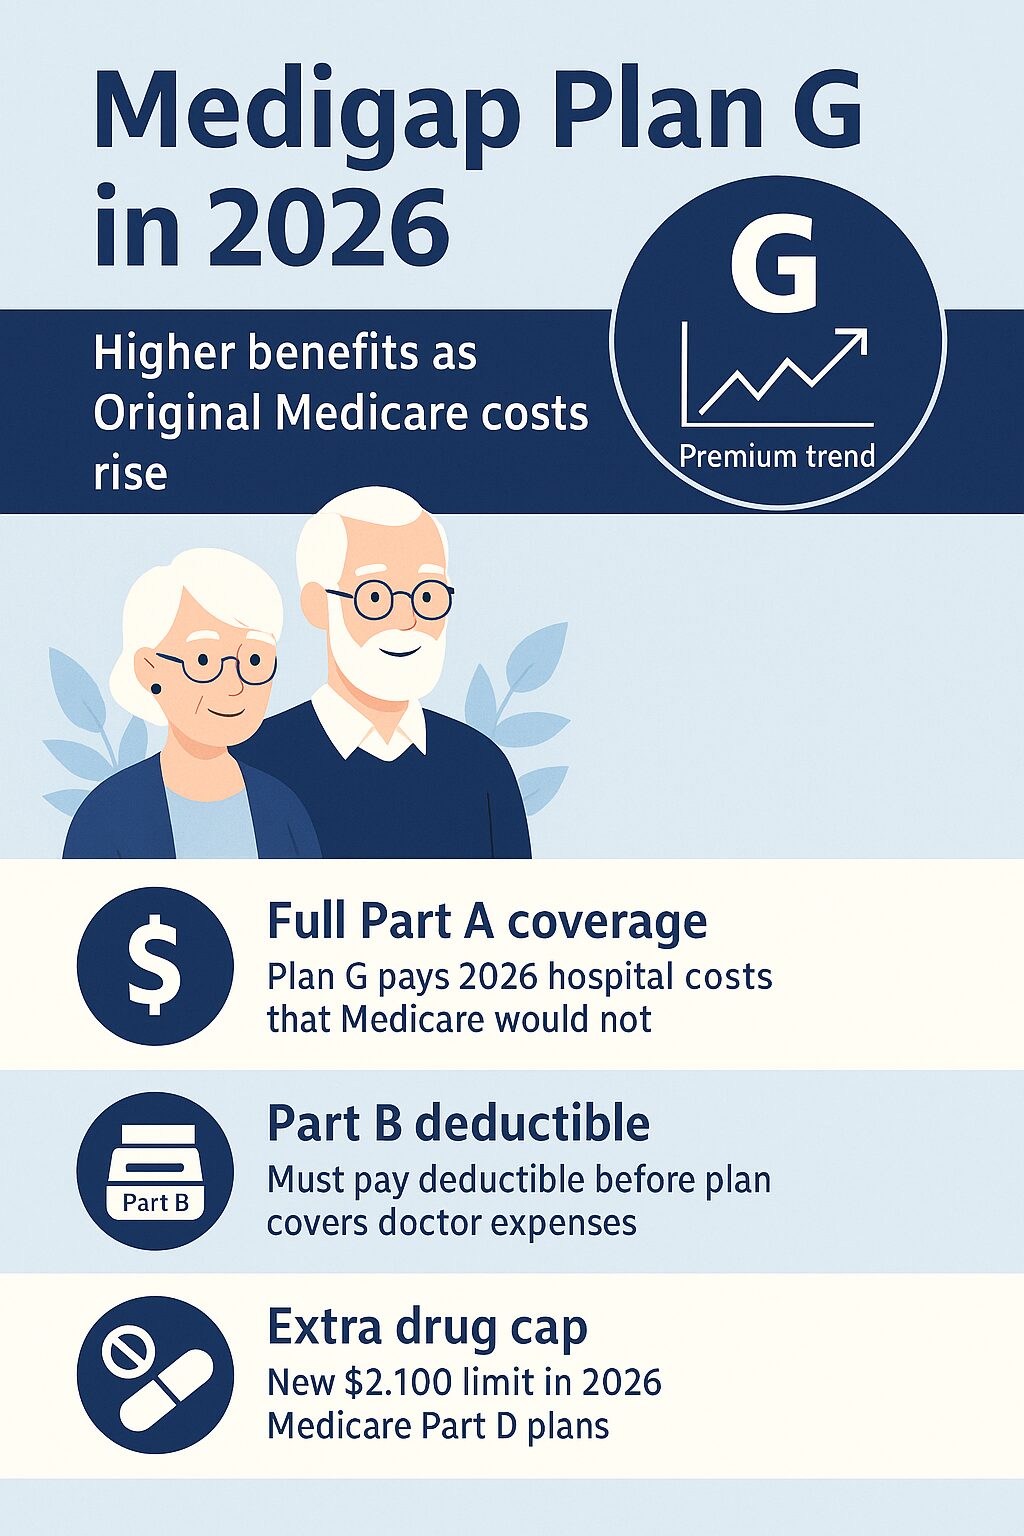
For that, you'll need a separate Medicare Part D plan. AARP/UnitedHealthcare is the very best Medicare Supplement company overall since it has cost effective rates and great client fulfillment. This suggests that Medicare Supplement Plan G from AARP/UnitedHealthcare gives you the same protection as Strategy G from Aetna, Blue Cross or any other company.

Latest Posts
Cheap Individual Health Quotes

Comparing PPO and HMO Health Plans

Comprehensive Guide to 2026 Medicare Part D Enrollment